For restaurants Covid-19 was a crisis – pandemic loans are proving a disaster
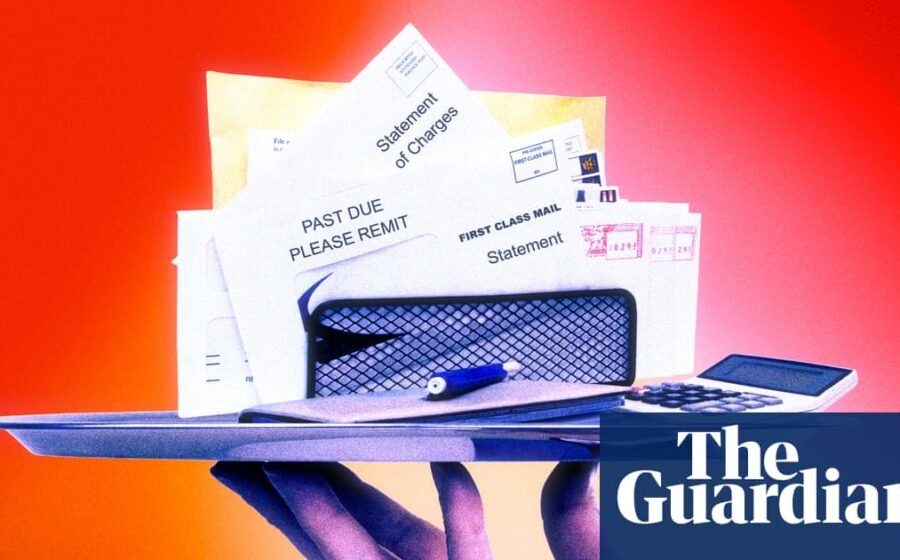
Low-interest loans kept many eateries afloat. But the industry never recovered enough for them to repay the debt
For almost 20 years, Jai Mazumdar has served vegetarian curries, samosas, gulab jamun and other Indian delicacies at Spice N Curry, a cafe and grocery nestled inside a modest strip mall near Florida International University (FIU) in Miami. When the Covid-19 pandemic devastated his business, as it did with so many restaurants, Mazumdar took out a $370,000 economic injury disaster loan (EIDL) from the federal government in early 2021.
At the time, it provided a desperately needed lifeline. He was confident that once business returned to normal he could begin repaying the 30-year loan, which came with a low 3.75% interest rate and a 30-month deferment period. But when his business didn’t recover, the disaster loan turned out to be a disaster of its own.
-
U.S. Stocks Fall as Credit Fears Haunt Tech SectorMarketWatch Markets1 day ago
-
From Verizon to UnitedHealth, Corporate America Is Balking at ‘Tokenized’ StocksMarketWatch Markets1 day ago
-
It’s not just Commerzbank: Italians are eating up German businessThe Economist Finance1 day ago
Leave a Reply